The act of purchasing a property represents the most substantial financial transaction for the majority of Canadians during their lifetime. It also stands as their most significant investment. However, from a purely financial perspective, the decision between making a substantial down payment with higher monthly expenses as a homeowner or remaining a renter and directing savings elsewhere is a critical consideration. Which option ultimately leaves an individual with more financial resources in the long run?
Explore our simulator below. Continue reading to grasp how to utilize it effectively.
To address this inquiry, an examination of over two decades of historical data on property values, rental rates, inflation, interest rates in 22 Canadian metropolitan regions, along with long-term stock market returns, was conducted.
Leveraging this data, an interactive simulator was created. With each simulation run, it computes the monthly expenses and financial gains for three distinct scenarios: a homeowner with a fixed-rate mortgage, one with a variable-rate mortgage, and a renter. Whenever the renter’s monthly expenses fall below those of the homeowner, the surplus is automatically channeled into stocks and bonds to grow over time.
The simulator forecasts these financial trajectories over a 25-year span across 1,000 unique scenarios. These scenarios encompass various conditions, from high rental costs and low interest rates to average inflation combined with subdued stock market returns.
The calculations consider mortgage payments, insurance, property taxes, maintenance expenses, condo fees, rent, and eventual selling costs. Each outcome represents a potential future based on historical trends and the selections made.
Naturally, predicting the future remains an uncertain endeavor. This tool offers probabilities, not certainties, and should not dictate major financial choices. Below is a simplified version of our simulator. A more detailed iteration with expanded choices and an in-depth methodology breakdown is available towards the end of this article.
Shifts in Home Prices and Stock Market Performance
The simulator, while valuable, is imperfect. Past performance does not guarantee future outcomes, and numerous macroeconomic factors are poised to evolve. Canada’s population is aging, immigration prospects remain uncertain, an AI market bubble could disrupt stock markets, and numerous variables continuously reshape the broader economic and housing landscapes.
Due to the constraints of comprehensive historical data, the tool focuses on the last 25 years, omitting Canada’s significant housing crash in the early 1990s. Several experts caution that property maintenance costs are often underestimated, particularly when unforeseen issues like roof leaks arise. Additionally, in reality, few Canadians reside in the same home for a quarter-century.
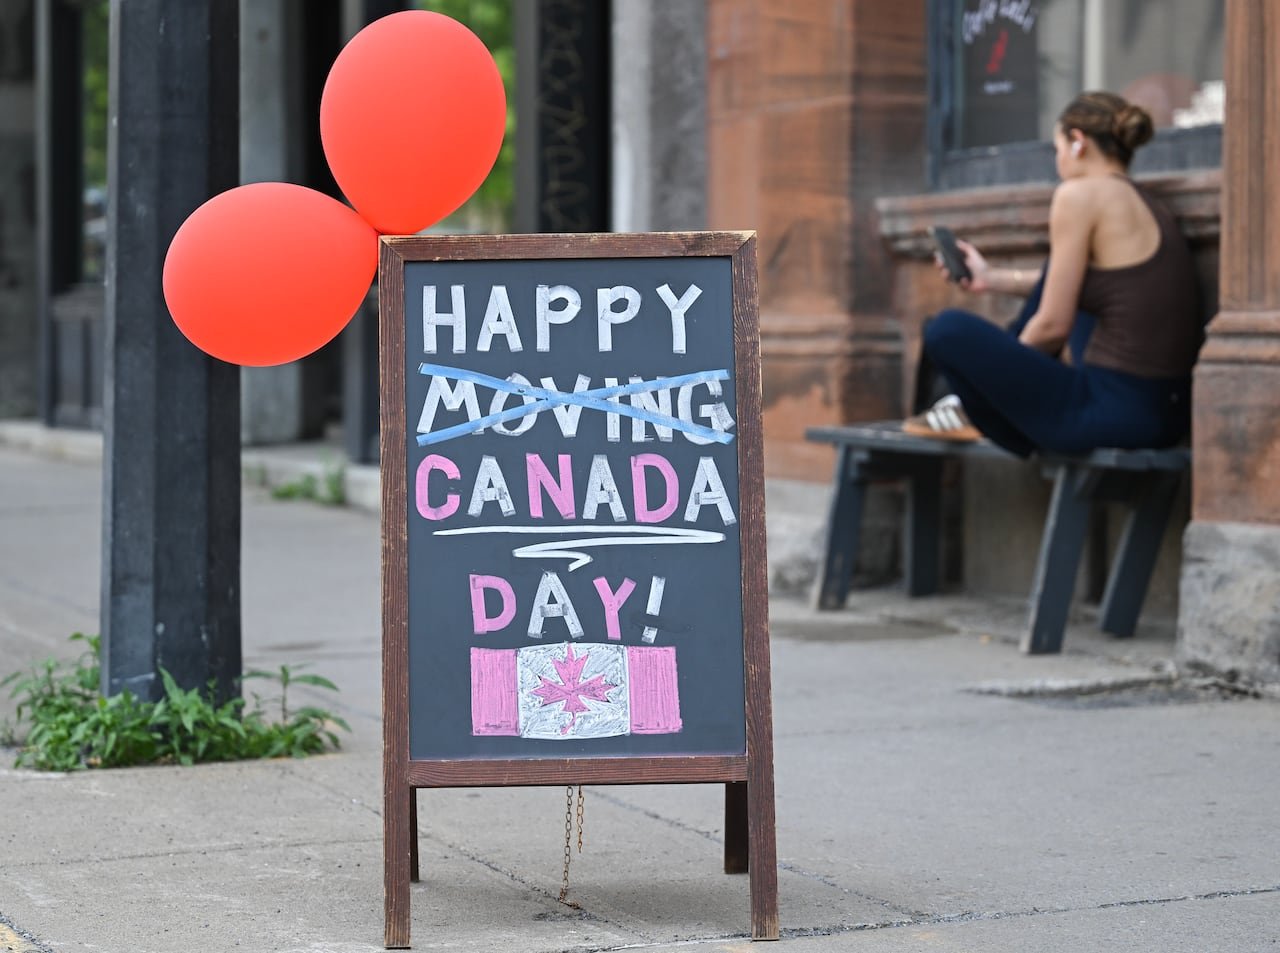
A sandwich board is shown on a street on Quebec’s unofficial moving day in Montreal on July 1. (Graham Hughes/The Canadian Press)
Nevertheless, property values have experienced a decline in recent years, whereas interest rates, average property taxes, and maintenance expenses have risen.
Conversely, the stock market has seen notable growth. An investment initiated in 2005 would be approximately seven times more valuable today, in contrast to a property purchased at the same time, which would have tripled in worth.
Based on this analysis, a clear trend emerges: Opting to rent an average studio or one-bedroom apartment and diligently investing the saved funds from not owning a